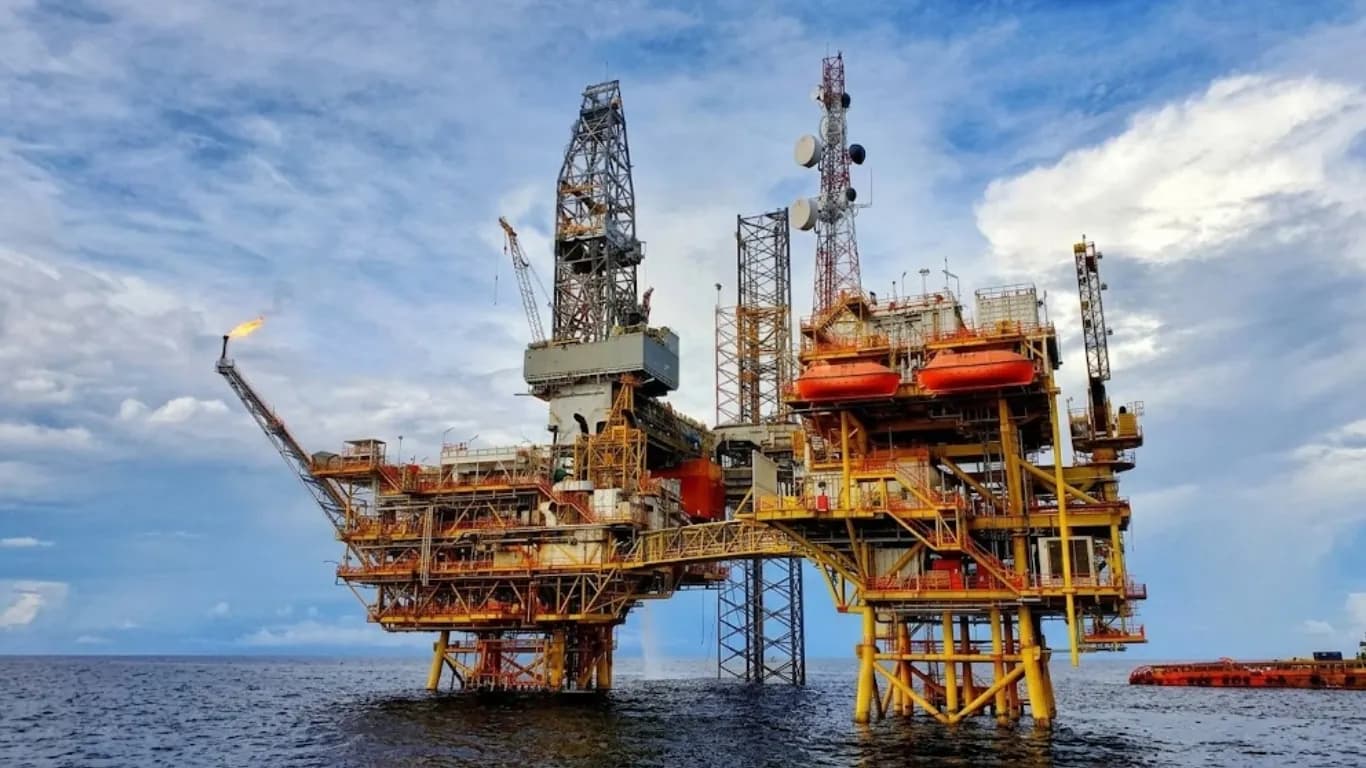
On July 31, 2026, the Union Cabinet cleared ₹84,084 crore for something India has attempted, in smaller and harder ways, three times before.
It's called Samudra Manthan , the National Offshore Exploration Scheme. The ₹84,084 crore financial outlay runs through FY2030-31 , roughly five fiscal years from approval , while ONGC has separately stated a plan to drill 150 deepwater wells over seven years, a slightly longer horizon than the scheme's own funding window. ONGC estimates its target basins hold 5,600+ MMTOE of deepwater and ultra-deepwater hydrocarbon potential, while the scheme's own stated goal is more conservative: adding over 600 MMTOE of confirmed reserves , the gap between geological upside and what's actually expected to be proven and produced.
To run it, ONGC stood up DeepX , its Deepwater Exploration Mission Centre , in Mumbai on January 5, 2026, a mission-mode team integrating geoscientific expertise, seismic interpretation, specialised training and global collaborations under a "One Company, One Data" philosophy. Less than seven months later, on July 25, 2026, Union Petroleum Minister Hardeep Singh Puri virtually spudded the mission's first well , MN-DW18-1-H-D , from New Delhi, six days before the Cabinet formally approved the ₹84,084 crore outlay.
It's the biggest number India has ever put behind offshore exploration. But it isn't India's first rodeo in deep water. And the three campaigns that came before it , one ONGC, one GSPC, one RIL-BP , are the reason Samudra Manthan doesn't have to start from a blank notebook.
This is that history, laid out honestly. Not a "past failures vs. present triumph" story. A capability-accumulation story, where every campaign , successful or scarred , left the next one smarter.
Launched in August 2003, Sagar Samridhi was, at the time, described as the biggest deepwater exploration campaign ever undertaken by a single operator anywhere in the world.
"The team is gaining knowledge about deepwater drilling technology. A few years hence, ONGC will be in a position to undertake deepwater drilling on its own."
The numbers were audacious for a company with almost no deepwater track record:
- 47 deepwater wells planned, the deepest targeting 6,000 metres of water , beyond the US Gulf of Mexico's then-record of 3,050m
- A daily contractor payment of $750,000 under a new risk-sharing drilling model ,ONGC's first real exposure to how deepwater rig economics actually work
- First discovery came fast: the drillship Vijay Sagar tested gas at well G4-AB off Yanam, in a Pliocene channel-fan system, with flow rates of 14.42 MMcf/d
This campaign didn't hand ONGC a giant field overnight. What it handed ONGC was infrastructure, personnel, and process , the acquisition of deepwater-capable assets and a generation of engineers who had never before touched sub-2,000m water.
That capability is what eventually became KG-DWN-98/2 , split into Clusters I, II and III, with ONGC committing a further ₹65,000 crore (~$9–10 billion) for the three-cluster build-out, Cluster III alone extending to ~2,600m water depth. The Cluster-2 development became one of Asia-Pacific's largest and most complex subsea projects: a $5 billion, 34-well programme with 26 deepwater trees, executed with McDermott, Baker Hughes and L&T Hydrocarbon Engineering.
The payoff arrived on March 2, 2024, when Prime Minister Modi flagged off the first crude tanker, Swarna Sindhu, from KG-DWN-98/2 , a field developed at an investment of over ₹41,000 crore, expected to add 7% each to India's domestic oil and gas output at peak, with total lifecycle output projected at 30.5 billion cubic metres of gas and 14.24 million tonnes of oil from Cluster-2 alone.
The U Field's first well - U-3-B - was monetised in 11 months, among the fastest deepwater well-to-production timelines anywhere in the world.
The throughline: Sagar Samridhi was the tuition. KG-DWN-98/2 was the return on it. Twenty years is a long payback period , but it's a payback ONGC actually collected.
GSPC's KG-OSN-2001/3 block , christened the Deendayal Upadhyaya field , was awarded in NELP's third round in 2003, the same year Sagar Samridhi launched. The discovery, made in 2005, arrived with headline reserve estimates of 20–21 trillion cubic feet, at one point pitched as nearly three times the size of RIL's KG-D6.
Part of why it took so long is genuine geological difficulty: Deendayal is a high-pressure, high-temperature (HPHT) reservoir, with wells drilled to roughly 5,000 metres below the seabed , pressures around 15,000 psi at wellhead, temperatures near 152°C. In 2016, GSPC used hydro-fracturing in an HPHT offshore environment at that depth for the first time in India, bringing in globally established names , Halliburton, Barry & Associate, E-Frac and Xodus , to execute it.
The reality that followed is one of the harder lessons in Indian upstream history:
- Independent certification by Gaffney Cline eventually settled reserves at 14.4 tcf company-wide, with DGH certifying only 1.8 tcf at Deendayal West specifically
- By March 2015, the CAG found GSPC had spent $2.8 billion against a sanctioned field development estimate of $2.75 billion , with 12 more development wells still incomplete; by GSPC's own FY16 disclosure, that figure had risen to $3.6 billion invested, against roughly ₹19,500 crore of associated debt
- E&P-linked liabilities nearly doubled in three years to ₹20,038 crore by FY15
- A subsequent CAG report on Gujarat's state PSUs flagged an impairment loss of ₹14,924 crore (₹149.24 billion) on GSPC's participating interest in the block , the single largest loss among all Gujarat state enterprises that year
In 2016–17, ONGC stepped in , acquiring GSPC's entire 80% stake and operatorship in the Deen Dayal West field for ₹6,443 crore, plus ₹1,295 crore for rights to the block's other discoveries, roughly ₹7,738 crore in total.
Recommended by LinkedIn
The lesson this campaign left behind wasn't technical , it was structural. Deendayal was a reminder that reserve estimates need independent, early, third-party certification before they enter public and investor discourse; that field development plans need contingency built in for deepwater's cost overruns as standard, not exception; and that a state entity taking large operator risk in an unfamiliar basin needs the balance sheet , and the in-house deepwater bench , to absorb a multi-year gap between capex and cash flow. ONGC's absorption of the block folded that hard-earned geological data into the same national deepwater knowledge base that Samudra Manthan draws on today.
If Sagar Samridhi built capability and Deendayal tested discipline, KG-D6 is the campaign that proved India could actually run a world-class deepwater asset at scale , while also generating the country's longest-running upstream legal saga.
The high point came fast. When the D1 and D3 fields came online in April 2009, India's natural gas availability doubled overnight. Production peaked at 69.43 mmscmd in March 2010 , 66.35 mmscmd from D1&D3 alone, the largest of 18 discoveries across the block.
Then came the fall, and the fights.
- By 2012–13, geological complications ,water and sand ingress, sharper-than-modelled reservoir pressure drops , had pulled output down in stages: ~35 mmscmd (2012–13) → ~9.7 mmscmd (2015–16) → a low of 4.9 mmscmd in Q3 FY18, a collapse of roughly 93% from the March 2010 peak
- The government read the shortfall differently: as non-drilling of committed wells against an approved $8.8 billion investment plan, and imposed a cumulative penalty that reached $2.376 billion across FY11–FY14 for missed production targets, applied as disallowed cost recovery under the PSC , followed by a further ₹1,700 crore penalty in January 2018 as the shortfall continued
- A separate dispute , over alleged gas migration from ONGC's adjoining blocks into KG-D6 , produced a $1.55 billion government claim; arbitration found in RIL's favour, the Delhi High Court's single-judge bench upheld that in May 2023, before a division bench later overturned it on government appeal. The government's demand in that dispute has since been revised upward to $2.81 billion
- A related, newer dispute over disallowed development costs , a $247 million claim , has been in international arbitration, with resolution expected by early 2026
- Combined, government claims and counterclaims across KG-D6's various disputes have been reported as high as $30 billion
- D1&D3 , India's first deepwater gas field , underwent a planned, safe cessation of production in February 2020, having already outlasted its original technical life expectancy of 2015 through RIL-BP's own intervention
And then, the second act. RIL and BP floated a $5 billion redevelopment plan as early as 2013; execution accelerated from 2017. Production resumed in phases from December 2020 with the R-Cluster, followed by the Satellite and MJ fields. By Q1 FY24, the "second wave" hit a new peak of 30.6 mmscmd , KG-D6 alone now contributing roughly 30% of India's entire domestic gas production.
That peak, too, has since rolled over. Natural reservoir depletion accelerated from mid-2025; by the June 2026 quarter, output had fallen to 24.8 mmscmd , down 19% from peak and ~7% year-on-year, contributing to a 3% contraction in India's total domestic gas output for the half-year. Price realisation softened alongside volumes , $8.89 per MMBtu, down from $9.97 a year earlier , even as oil/condensate realisation rose to $107.4/barrel. RIL has responded with four planned infill wells targeting ~220 BCF of incremental gas and three workover wells through FY27.
The lesson KG-D6 leaves behind is really two lessons, side by side. Technically, it's proof that Indian Deepwater fields can be engineered, monetized, and even revived at global-class execution speed. Commercially and contractually, it's a two-decade case study in how much uncertainty gets created when disputes over shortfall, migration, and cost recovery run in parallel with , rather than ahead of , field development. Samudra Manthan's built-in dispute-resolution and common-infrastructure provisions read, in part, as a direct answer to this history.
What This Actually Adds Up To
None of these three campaigns is a cautionary tale on its own. Put together, they're the reason Samudra Manthan isn't a leap of faith:
- From Sagar Samridhi, India got its first deepwater-capable engineering workforce and contractor relationships , the direct ancestry of KG-DWN-98/2's 11-month well-to-production record.
- From Deendayal, the sector learned, at real financial cost, why reserve certification and capital discipline have to come before the headlines.
- From KG-D6, India got proof that a deepwater asset can be engineered and revived at genuinely world-class pace , and a two-decade lesson in how expensive it gets when commercial disputes run alongside field development instead of ahead of it.
But underneath the campaign-by-campaign story is a bigger one: India itself changed.
In 2003, the honest question was whether Indian operators could execute deepwater exploration at all. By 2026, that question has moved on , it's no longer can we drill deep water, it's can we convert that capability into repeatable, commercially disciplined discoveries and production, on a national scale, on a predictable timeline. That's a materially harder question, and it's the one Samudra Manthan is actually being asked to answer.
Samudra Manthan isn't starting a new story. It's the next chapter of one India has been writing, well by well, since 2003.
With DeepX's "One Company, One Data" approach running since January 2026, the Andaman basin's already-established thermogenic gas signals, live drilling now underway at Mahanadi, and a dedicated Oil & Gas Manufacturing and Services Zone meant to build domestic capability rather than import it, the mission is explicitly built to compress the years-long lag between discovery and decision that cost the earlier campaigns time and money.
Geoscientists, drillers, and ONGC veterans , you've lived through more than one of these cycles. Where do you think Samudra Manthan is genuinely different this time, and where is it repeating a bet India has already placed?
Happy Reading!
Disclaimer: I'm not a geologist or a petroleum engineer. I've researched, verified, and collated publicly available information here as carefully as I could. Any errors are mine , corrections from those closer to the subject are always welcome.